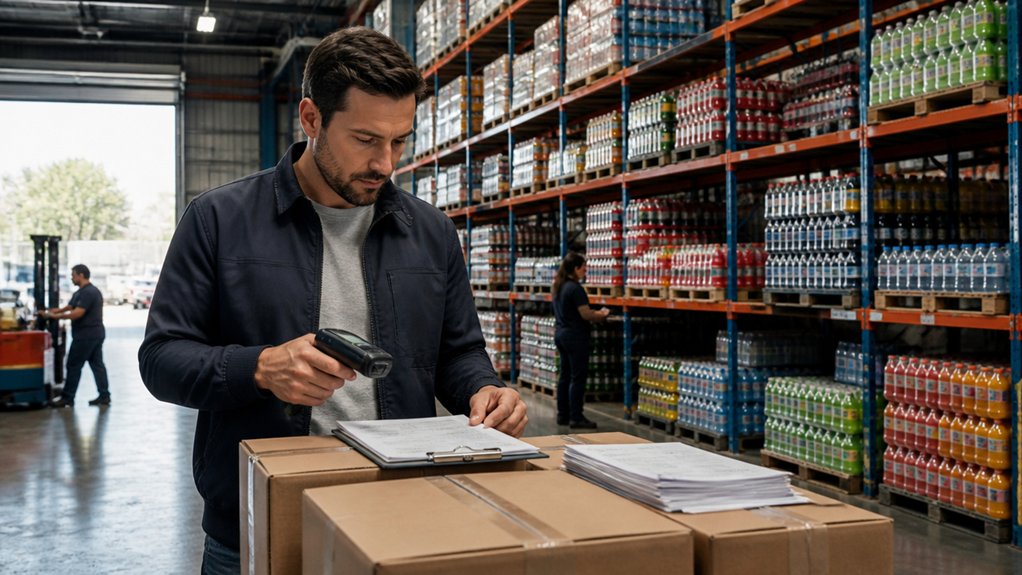
As your beverage brand grows, production costs may fall due months before retailers pay for stock. That timing gap can put pressure on cash just as you are funding larger production runs, seasonal demand and day-to-day operations.
Before choosing finance or setting repayment dates, bring together your supplier terms, stock turnover and sales forecasts. I advise growing businesses to start with a practical question: when will cash actually come in, and what commitments must it cover before then?
A sound plan can support growth without tying up too much working capital. But it must reflect the way money moves through your business, not just the size of the order. This is general information, not financial advice.
Why Beverage Growth Creates Cash-Flow Gaps
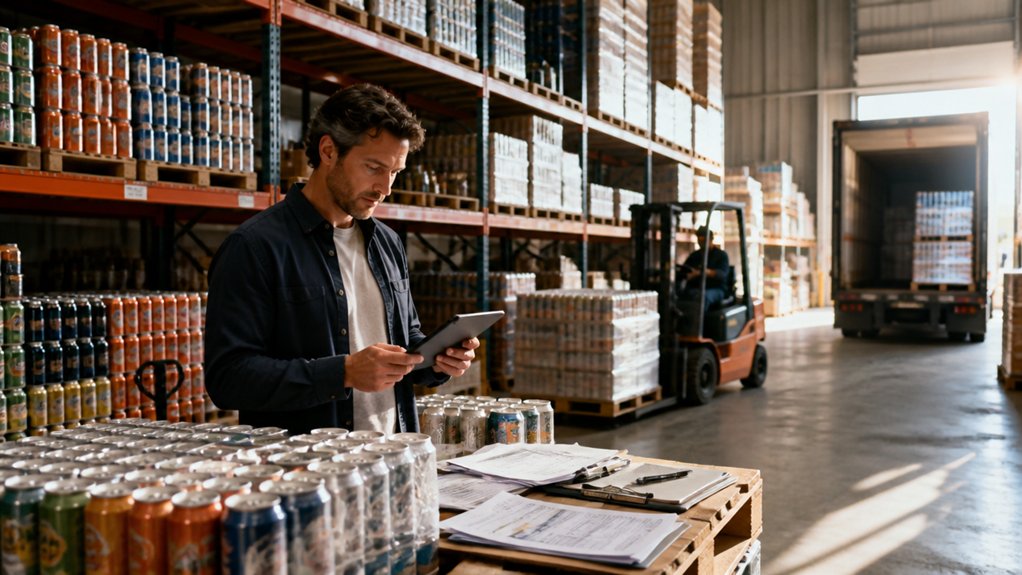
Stronger sales can leave a beverage business short of cash. Ingredients, packaging and production often need to be paid for before retailers settle their invoices. As orders grow, these costs can rise faster than cash coming in, even when revenue looks healthy.
Seasonality can widen the gap. You may need to build stock months before peak demand, while sales arrive later and unevenly. Longer payment terms add to the delay, and rapid growth can mean more cash tied up in each production cycle. Supplier credit may help, but it may not stretch far enough to cover larger orders.
I advise leaders to monitor payment times, stock turnover and seasonal forecasts together. Use them to estimate when cash will be needed, then decide how much inventory to build and whether production can be phased. The aim is to spot a shortfall early and preserve room to meet operating costs.
How Beverage Inventory Financing Works
Once you have mapped the gap between paying suppliers and receiving sales income, inventory financing may help fund stock in the meantime. You borrow against eligible inventory and repay as products sell. Before proceeding, consider three points:
- How the stock is valued: Lenders may consider product cost, shelf life, demand and resale potential. Perishable or slow-moving stock may support a lower valuation.
- How much you can borrow: The lender’s advance rate determines the proportion of approved inventory value available to you. A borrowing limit may also cap the amount you can draw.
- When repayment is due: Sales proceeds may reduce the balance, but the repayment schedule should reflect realistic sell-through forecasts and supplier terms.
I would review stock turns, margins and sales forecasts regularly. Reliable inventory data helps you judge how much to borrow and avoid tying up working capital in excess stock.
This is general information, not financial, legal or investment advice.
Which Financing Options Fit Your Production Run?
The right financing option depends on the size and timing of your production run, and how confidently you expect to sell it.
For a smaller batch, supplier credit may cover ingredients or packaging without the need for a separate loan. If you’re scaling a product with a proven sales record, an inventory-backed line may fund a larger run while leaving cash available for distribution.
Supplier credit can cover smaller runs, while an inventory-backed line may help fund larger batches of proven products.
Purchase-order financing may be worth considering when you have a confirmed retailer order but lack the working capital to meet the upfront production costs. Check the fees, advance rates, collateral requirements and funding times for each option. Then compare them with your production forecast and supplier quotes.
I would size any facility against conservative demand estimates, not an optimistic sales target. Avoid borrowing for stock your sales data doesn’t support, and choose repayment terms that fit the production cycle.
How Should Repayment Fit Your Sales Cycle?
Even a well-sized facility can put pressure on cash flow if repayments fall due before sales revenue arrives. Set the schedule around your actual cash cycle: how quickly stock sells and when retailers pay, including any deductions or delays. Don’t base it on optimistic launch targets.
- Map when production, freight and other supplier costs fall due.
- Estimate when each sales channel is likely to pay, allowing for deductions and delays.
- Agree repayment milestones that reflect expected collections, with room for seasonal variation.
Compare weekly sales and collections with scheduled repayments. If there’s a gap, decide how to cover it without diverting cash needed for reorders or day-to-day operations.
If repayments are fixed, hold enough liquidity to cover the longest delay you reasonably expect in receiving payment. In my experience, a sound repayment plan should support the business’s growth rather than constrain it.
How Can You Forecast Cash Flow for Your Next Run?
Forecast cash flow for your next production run
Map every production cost and customer payment week by week to spot cash gaps before your next run begins.
Build a week-by-week forecast from the first supplier deposit to the final customer payment. Set out when you expect to pay for ingredients, packaging, freight, labour and marketing, and when cash is likely to arrive. The timing matters as much as the total: a profitable run can still put pressure on cash if costs fall due well before customers pay.
Base production volume on confirmed orders, sales trends and realistic forecasts for each channel. Then check the assumptions behind your plan: production lead times, supplier terms, payment milestones and expected customer collection dates. Allow for delays and slower sell-through, rather than assuming everything goes to plan.
The forecast should show the lowest cash balance during the run and the working capital needed to get through it. Compare a few plausible scenarios. If the cash gap is too large, consider changing the order size, negotiating deposit timing or arranging finance before you commit.
I find it useful to review the forecast weekly against actual costs and collections. Update the assumptions as new information comes in, so you can act early if the run is taking more cash or longer to sell than expected.
This is general information, not financial, legal or investment advice.
— Angus Fleming, founder of Fleming Business Consultancy, London. I’m a former consultant to FTSE 100 and S&P 500 companies and now advise growing businesses worldwide.
Conclusion
Growth need not drain your cash reserves. Start by mapping the gap between paying suppliers and receiving money from customers. Then size each production run against confirmed demand, not an optimistic sales forecast.
Choose finance that suits the inventory and agree repayments that reflect when sales are likely to generate cash. I advise growing businesses to watch stock movement, seasonal changes and late payments closely; each can put pressure on working capital before it becomes obvious.
Ask what another production run would cost if customer payments arrived a month late. Include that possibility in your cash-flow plan, and keep enough liquidity for day-to-day operations. Disciplined decisions about stock and finance can support growth without putting the business under avoidable strain.