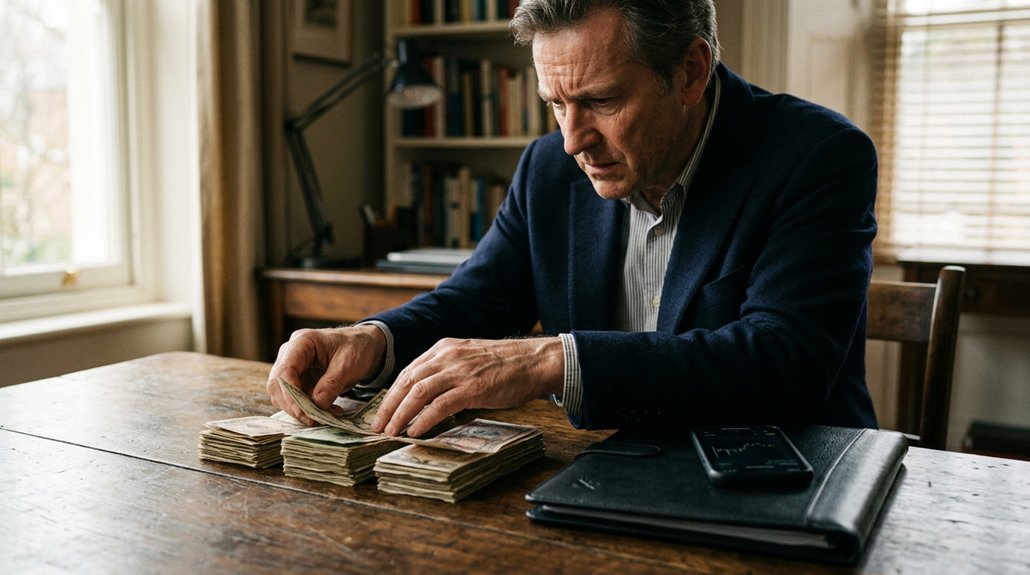
Cash can feel safer because it is visible, accessible and unlikely to change in value overnight. That sense of control may ease anxiety, but it can also make ordinary market movements seem more threatening than they are.
The practical question is whether holding cash supports your goals or simply helps you avoid the discomfort of uncertainty. I have seen how easily caution can become a default rather than a considered choice. Be clear about what you need cash for, how much access you require and what trade-offs you are willing to accept. This is general information, not investment advice.
Why Cash Feels Safer Than Investing
Cash offers visibility and immediate access. You can see the balance and avoid the daily price movements that come with investments. That can create a sense of control, particularly when you may need the money soon.
But a stable balance isn’t the same as stable buying power. Inflation can gradually reduce what cash will buy, while investment values can rise or fall over time. The right balance depends on when you expect to use the money and what it needs to do.
I encourage business leaders to separate near-term cash needs from longer-term reserves. Keep enough readily available to meet planned spending and unexpected demands, then consider how the rest should be held in light of its purpose and time horizon. Treat cash as useful, not risk-free, and review the balance as circumstances change.
This is general information, not financial or investment advice.
How Fear Shapes Investing Decisions
Fear can make a short-term market fall feel like a reason to avoid investing altogether. When prices drop, it’s easy to mistake volatility for lasting danger. Loss aversion can add to the pressure: a possible loss may feel more significant than an equivalent gain.
You might respond by delaying an investment, holding more cash than your plans require or selling during a downturn. These choices can ease anxiety in the moment, but they may not serve your longer-term goals.
Before acting, ask what’s changed: the evidence, your financial plans or simply how comfortable you feel. I find that separating those questions can help you make a more considered decision. This is general information, not investment advice.
How to Balance Cash Savings and Investing
Cash savings and investments serve different purposes. Cash provides access to money for emergencies and near-term costs. Investments are for goals that are further away and can withstand fluctuations in value.
Start by listing essential expenses and likely costs over the coming months. Set aside enough cash to meet those needs without having to sell investments at an inconvenient time. The right amount depends on your circumstances, including how predictable your income is.
Then consider investing money you don’t expect to need soon. Choose a diversified portfolio that reflects your time horizon and your ability to tolerate losses. I find it useful to ask a practical question: if the value fell, would you still be able to stick to your plans?
Review your cash and investments when your income, expenses or goals change. The aim is to keep enough money accessible for near-term needs while giving long-term investments time to work. This is general information, not financial or investment advice.
Conclusion
Cash can feel reassuring because it is visible and readily available. But comfort alone is not a sound basis for deciding how to manage your money.
A fall in the value of investments can feel more threatening than an equivalent gain feels rewarding. That reaction may lead you to hold more cash than your needs require.
Set aside enough for emergencies and planned spending in the near term. Then consider how to allocate the rest in line with your goals, time horizon and tolerance for risk. Security and growth are not necessarily alternatives; a clear plan can make room for both.